
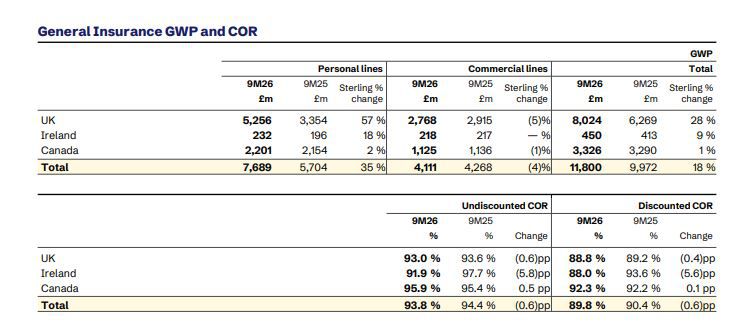
UK&I GI premiums were up 27% to GBP 8.5 billion (9M25: GBP 6.7 billion) with 54% growth in personal lines, supported by the acquisition of Direct Line and continued growth in Intermediated business. Commercial lines were 5% lower as Aviva maintained underwriting discipline to focus on profitability in current market conditions.
Canada GI premiums were up 2% in constant currency to GBP 3.3 billion (9M25: GBP 3.3 billion) with personal lines up 4% supported by pricing actions across auto and property, while commercial lines were flat as larger scheme wins in GCS have been partly offset by the competitive rating environment.
Group undiscounted combined operating ratio (COR) improved 0.6 pp to 93.8% (9M25: 94.4%) as strong rate adequacy and favorable prior year development were partly offset by elevated weather-related activity in Canada in Q3. Discounted COR was at 89.8% (9M25: 90.4%).
Wealth net flows of GBP 10.9 billion (9M25: GBP 8.3 billion) were up 31% representing 6% of opening Assets Under Management (‘AUM’), with strong growth in Workplace and Platform.
Aviva Investors delivered continued growth with total net flows of GBP 1.5 billion (9M25: GBP nil) and with c.65% of Workplace net flows going into Aviva Investors’ funds.
Estimated Solvency II shareholder cover ratio of 179% (HY26: 176%) benefitted from total capital generation over the quarter (+8 pp), partly offset by the interim dividend (-5pp). Total capital generation of 8 pp was driven by strong operating capital generation, despite the impact of elevated CATs in Canada, 2 pp of IWR management actions, and positive market movements from interest rate rises in Aviva’s core markets.
Aviva expects the solvency ratio to be in the high-180s by the end of 2026, including >7 pp from the remaining Direct Line capital synergies, subject to market movements. Solvency II debt leverage ratio was at 30.0% (HY26: 30.8%). Centre liquidity at the end of October 2026 was GBP 1.3 billion (July 2026: GBP 1.5 billion).
“Aviva is in great shape. Our performance has been excellent in the first nine months of 2026, demonstrating once again the benefits of scale across our diversified business. We continue to deliver strong, profitable growth, particularly in the capital-light areas of General Insurance and Wealth”, said Amanda Blanc, Group Chief Executive Officer. “We are confident about the remainder of 2026 and expect earnings per share to grow broadly in line with our target of 11% this year. Aviva’s continued strong trading, our strengths in artificial intelligence, and our leading market position, reinforce our confidence that we will meet our three-year financial targets and grow earnings over the longer term”, the Group CEO added.
The full report can be found here.
230 views

