

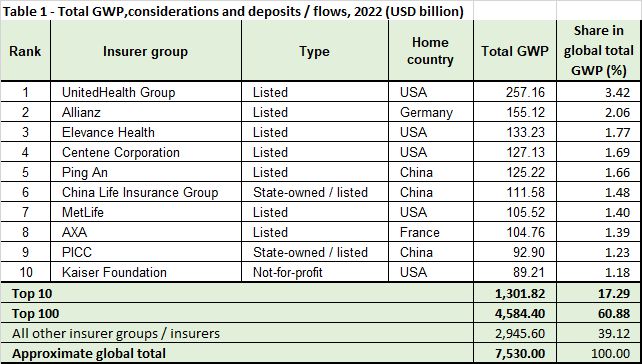
Top 100 insurance groups accounted for about 61% of the gross premiums written globally in 2022, while the Top 10 groups controlled a little over 17% of the approximate global total GWP of 7,530 USD billion, recent data provided by Insurance more show.
The marketing services and related consultancy provider Insuramore has recently released two global insurance groups’ rankings that together may be seen as a definitive global ranking of the top 100 insurer groups that takes into account GWP and related inflows across each of life / annuity, health and P&C (non-life) insurance as direct activity, plus reinsurance assumed.
The two rankings are:
- Total Gross Premiums Written, Considerations and Deposits / Flows Across All Types of (Re)Insurance Segmented by Major Line, 2022: Top 100 (Re)Insurer Groups Worldwide
- Gross Direct Premiums Written for Total P&C (Non-Life) Insurance Segmented by Major Line, 2022: Top 100 P&C Insurer Groups Worldwide
Allianz and AXA are the only European groups listed in Top 10. Most positions belong to US and Chineze players that operate in the largest global insurance markets. The leading position in the top is held by UnitedHealthcare Group,including the homonymous US insurer providing health benefit plans and services for large US national employers, senior citizens, but also state funded health insurance programs directed towards several demographic categories economically disadvantaged people. Active in the US and several countries of the Latin America, the Group ranks 10th in the 2023 Fortune Global 500.
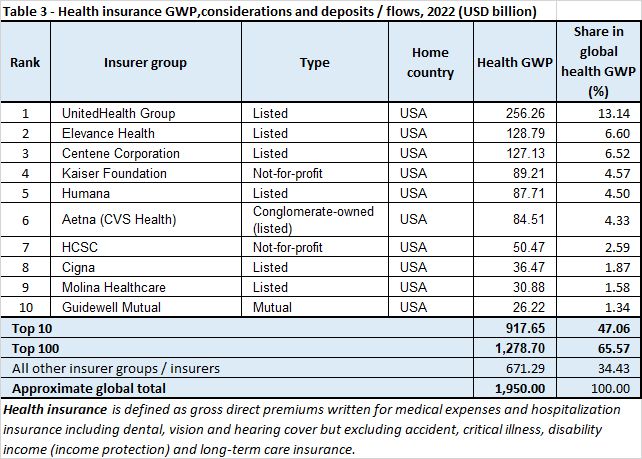
On the direct insurance side, the health insurance sector seems the most concentrated, with Top 100 insurance groups providing for about 65.5% of the total GWP of USD 1,950 billion, and Top 10 global players accounting for 47% of the total GWP. By comparison, the P&C (non-life) insurance appears as less concentrated, Top 100 insurance groups accounting for “just” about 56% of the global P&C GWP, while Top 10 players are weighting some 26.3%. On the life insurance segment, while Top 100 insurance groups accounted for about 60% of the global GWP (USD 2,980 billion), the weight of the Top 10 groups is superior to the total business average, reaching slightly over 21%.


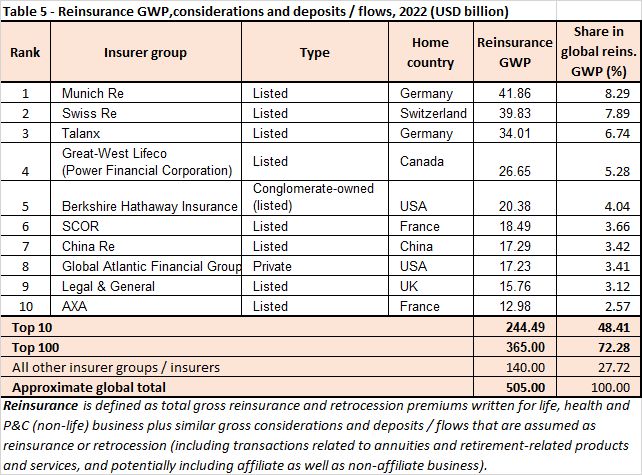
In the reinsurance field, the global market seems definitely controlled by the major players: while Top 100 reinsurance providers account for about 72% of the global reinsurance GWP production, the Top 10 group account for almost half of the total GWP. Munich Re and Swiss Re remain the biggest players in this market, with market shares of very close values (8.3% and 7.9%). According to Insuramore rankings, Talanx is the third contender, with a 6.7% market share.
Insuramore has also taken a closer look to the global P&C insurance business. While in comparison with other business lines, as health insurance, this segment seems less concentrated, it is still worth noting that the word’s largest 30 insurance groups providing P&C insurance are accounting for half of the global O&C insurance premiums production. Most of the groups listed in this group are making more than half of their GWP by writing commercial P&C insurance lines, thus covering the largest risks. In fact, only a few US based big retailers, as State Farm, Allstate or Assurant are included in the group despite their almost absent commercial insurance involvement. Also, looking at the groups with a lower presence on the commercial insurance side that are included in the Top 30 group, it is worth mentioning that for most of them motor insurance lines are the main GWP providers.
However, total figures show that overall, Commercial and Private (retails) P&C lines hold a rather equal share in the total P&C GWP, while motor insurance not only forms the main Private P&C business line, but also accounts for about 40% of the total P&C business. At the same time, home insurance only holds a much more lower share in the P&C portfolio, which may be at least in part the effect of the low insurance coverage rate of homes in many geographies.

Note: Insuramore research and estimates based on insurer group disclosures and insurance trade statistics (i.e. financial supervisory authorities, insurance trade associations etc.).
Data includes acquisitions completed by end December 2022 but not ones agreed by that date but scheduled for completion in 2023.
About Insuramore
Insuramore provides marketing services and related consultancy with a focus solely on the insurance sector which, globally, is forecast to be worth USD 11.5 trillion in premiums by 2040. Its insurance provider rankings provide original and unrivalled insights into carrier (underwriter) groups around the world. The full list of insurance types about which Insuramore can provide data, research and consulting services at an international level can be seen on the company’s website.

